
Europe

Marketing Communication. Capital at risk. For Professional Investors Only. Please read fund legal documentation before making any final investment decisions.
For much of the last three years, the U.S. manufacturing story has been easier to believe structurally than cyclically. Reshoring, automation, electrification, and defence modernisation all pointed to a larger domestic industrial base, but the near-term data remained uneven.
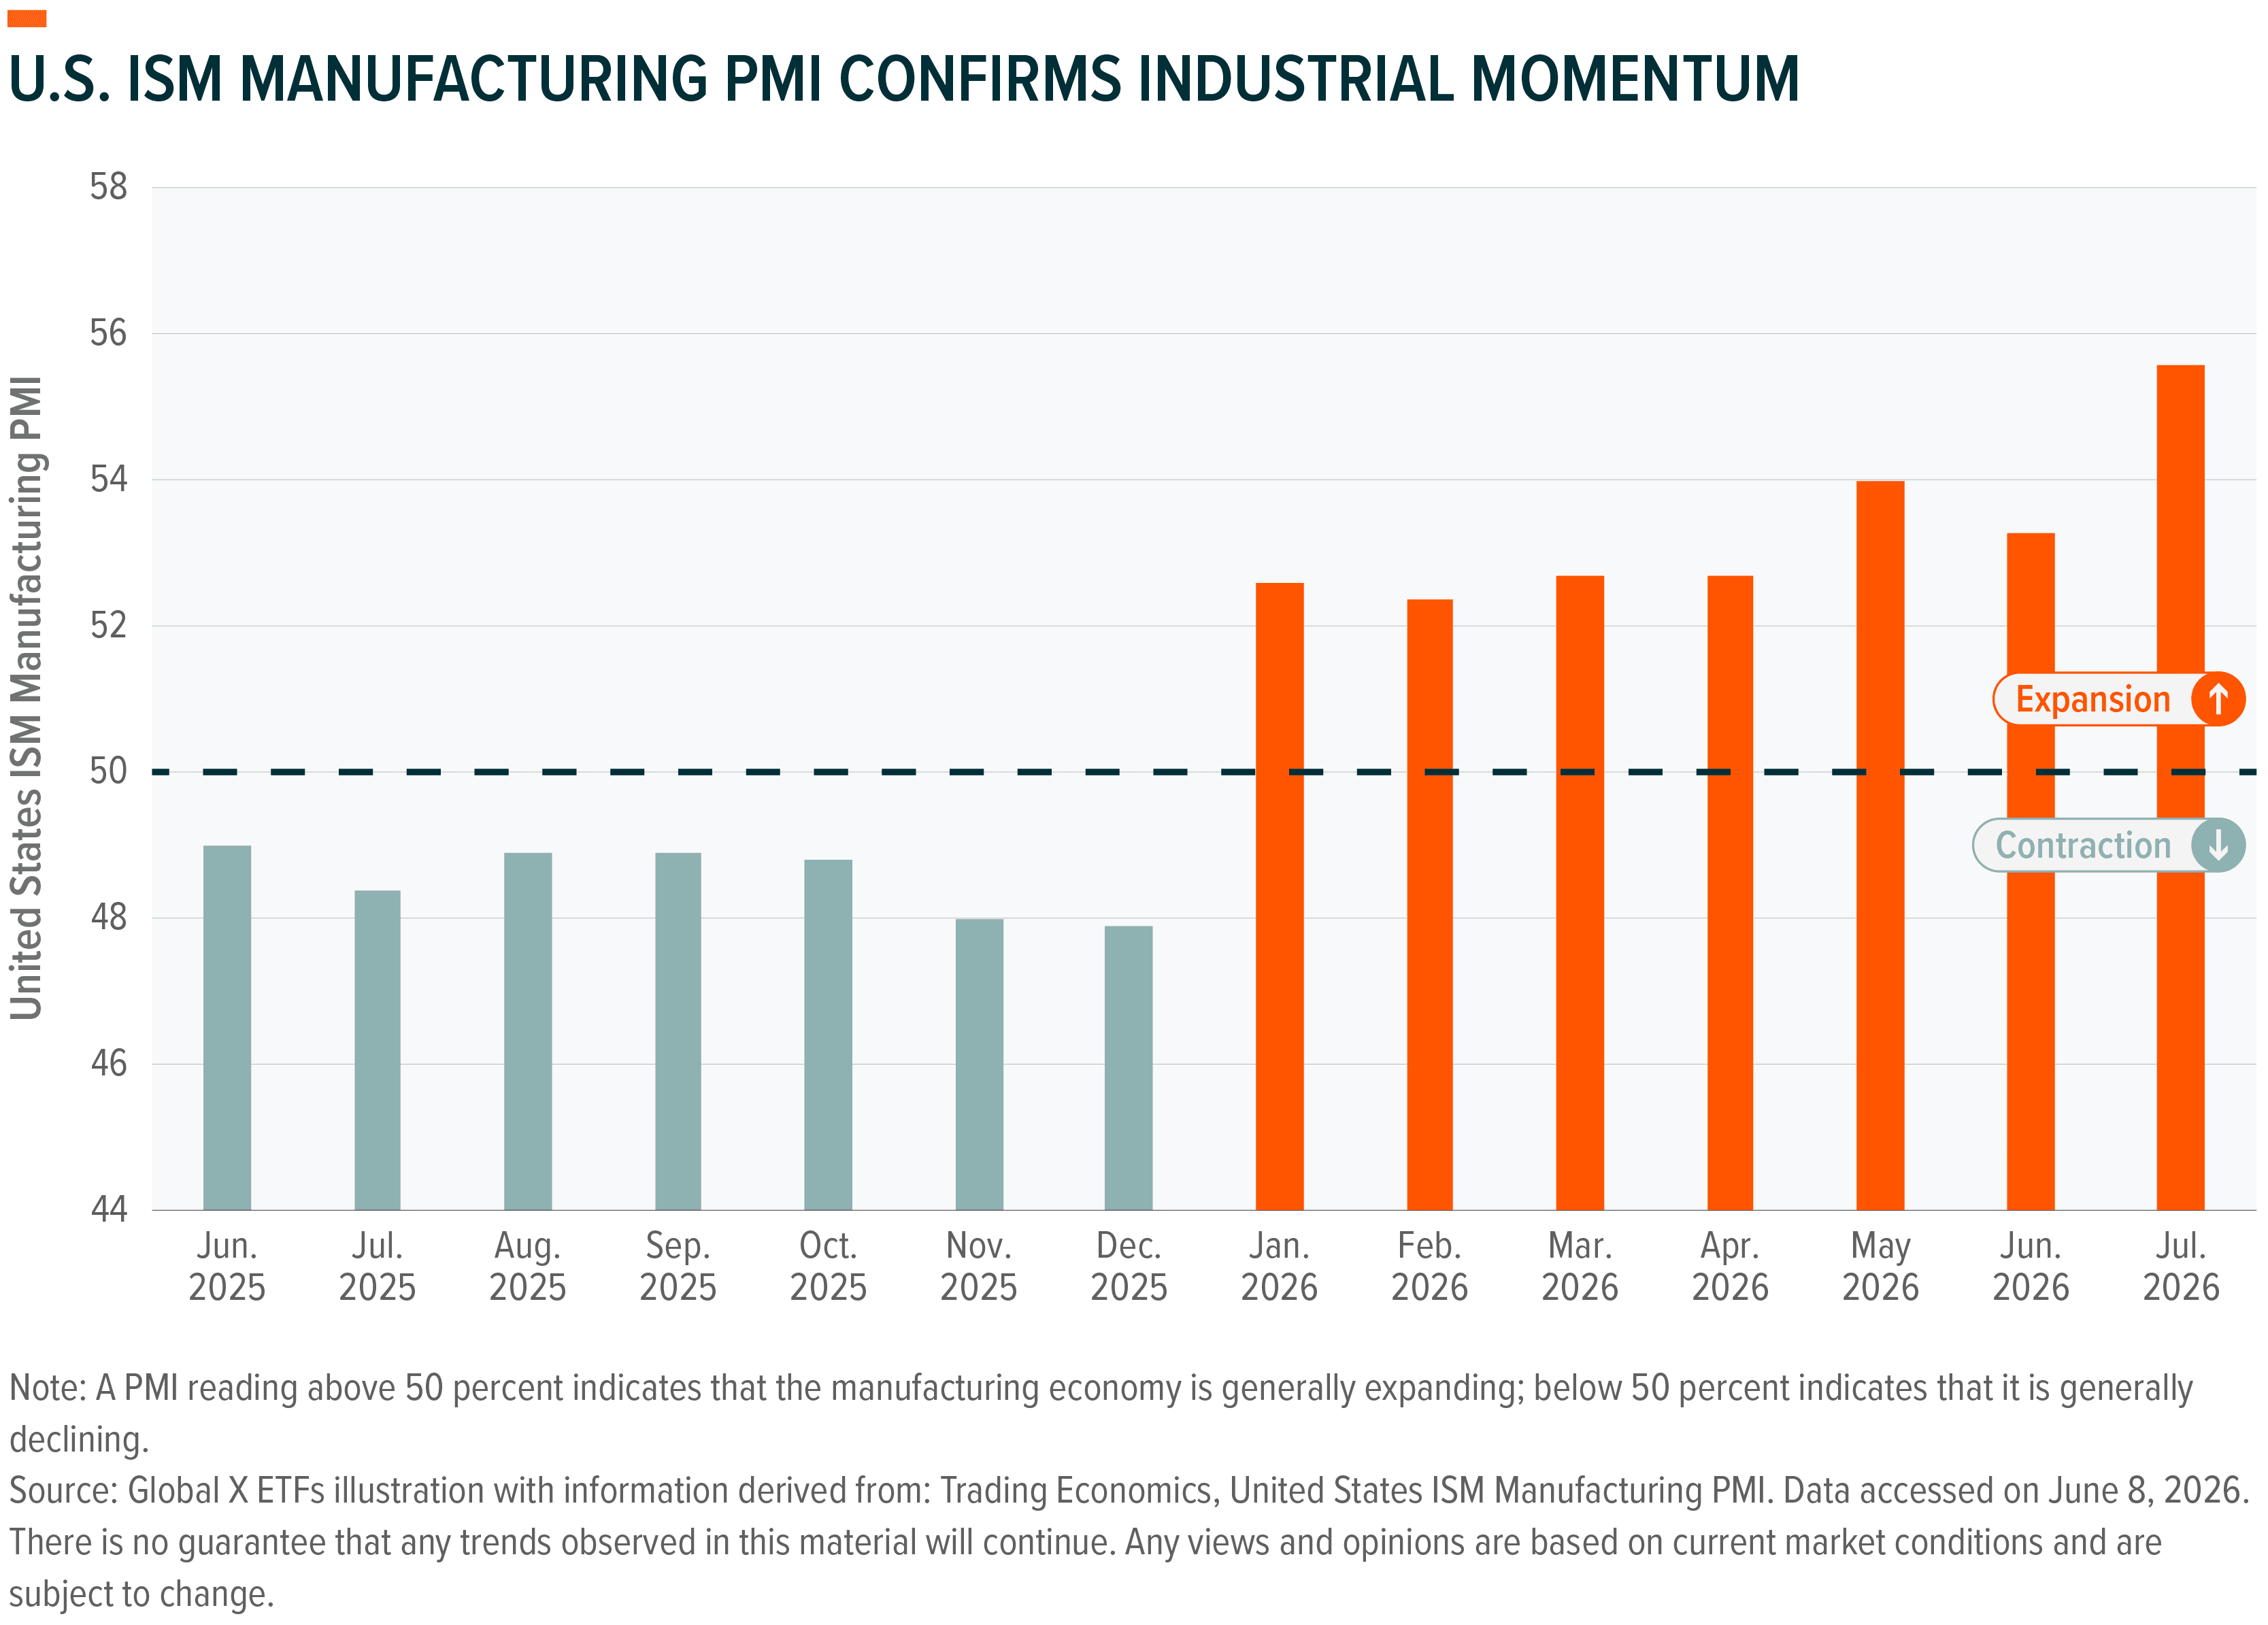
In 2026, that gap is closing, with industrial production trending positive, the Institute for Supply Management’s (ISM) Manufacturing PMI (Purchasing Manager’s Index) expanding for seven consecutive months,¹ and policy-sensitive sectors like steel showing early evidence of import substitution.² The manufacturing pipeline also remains substantial,³ led by semiconductors, pharmaceuticals, electrical equipment, and defence, creating a long runway for the domestic capacity buildout.
A full ramp-up will take time, but the direction of travel appears to have turned. Developments around the bottlenecks of American manufacturing could be a credible area of structural growth over the next several years, particularly across industrial automation, connectivity, power, infrastructure, and materials.
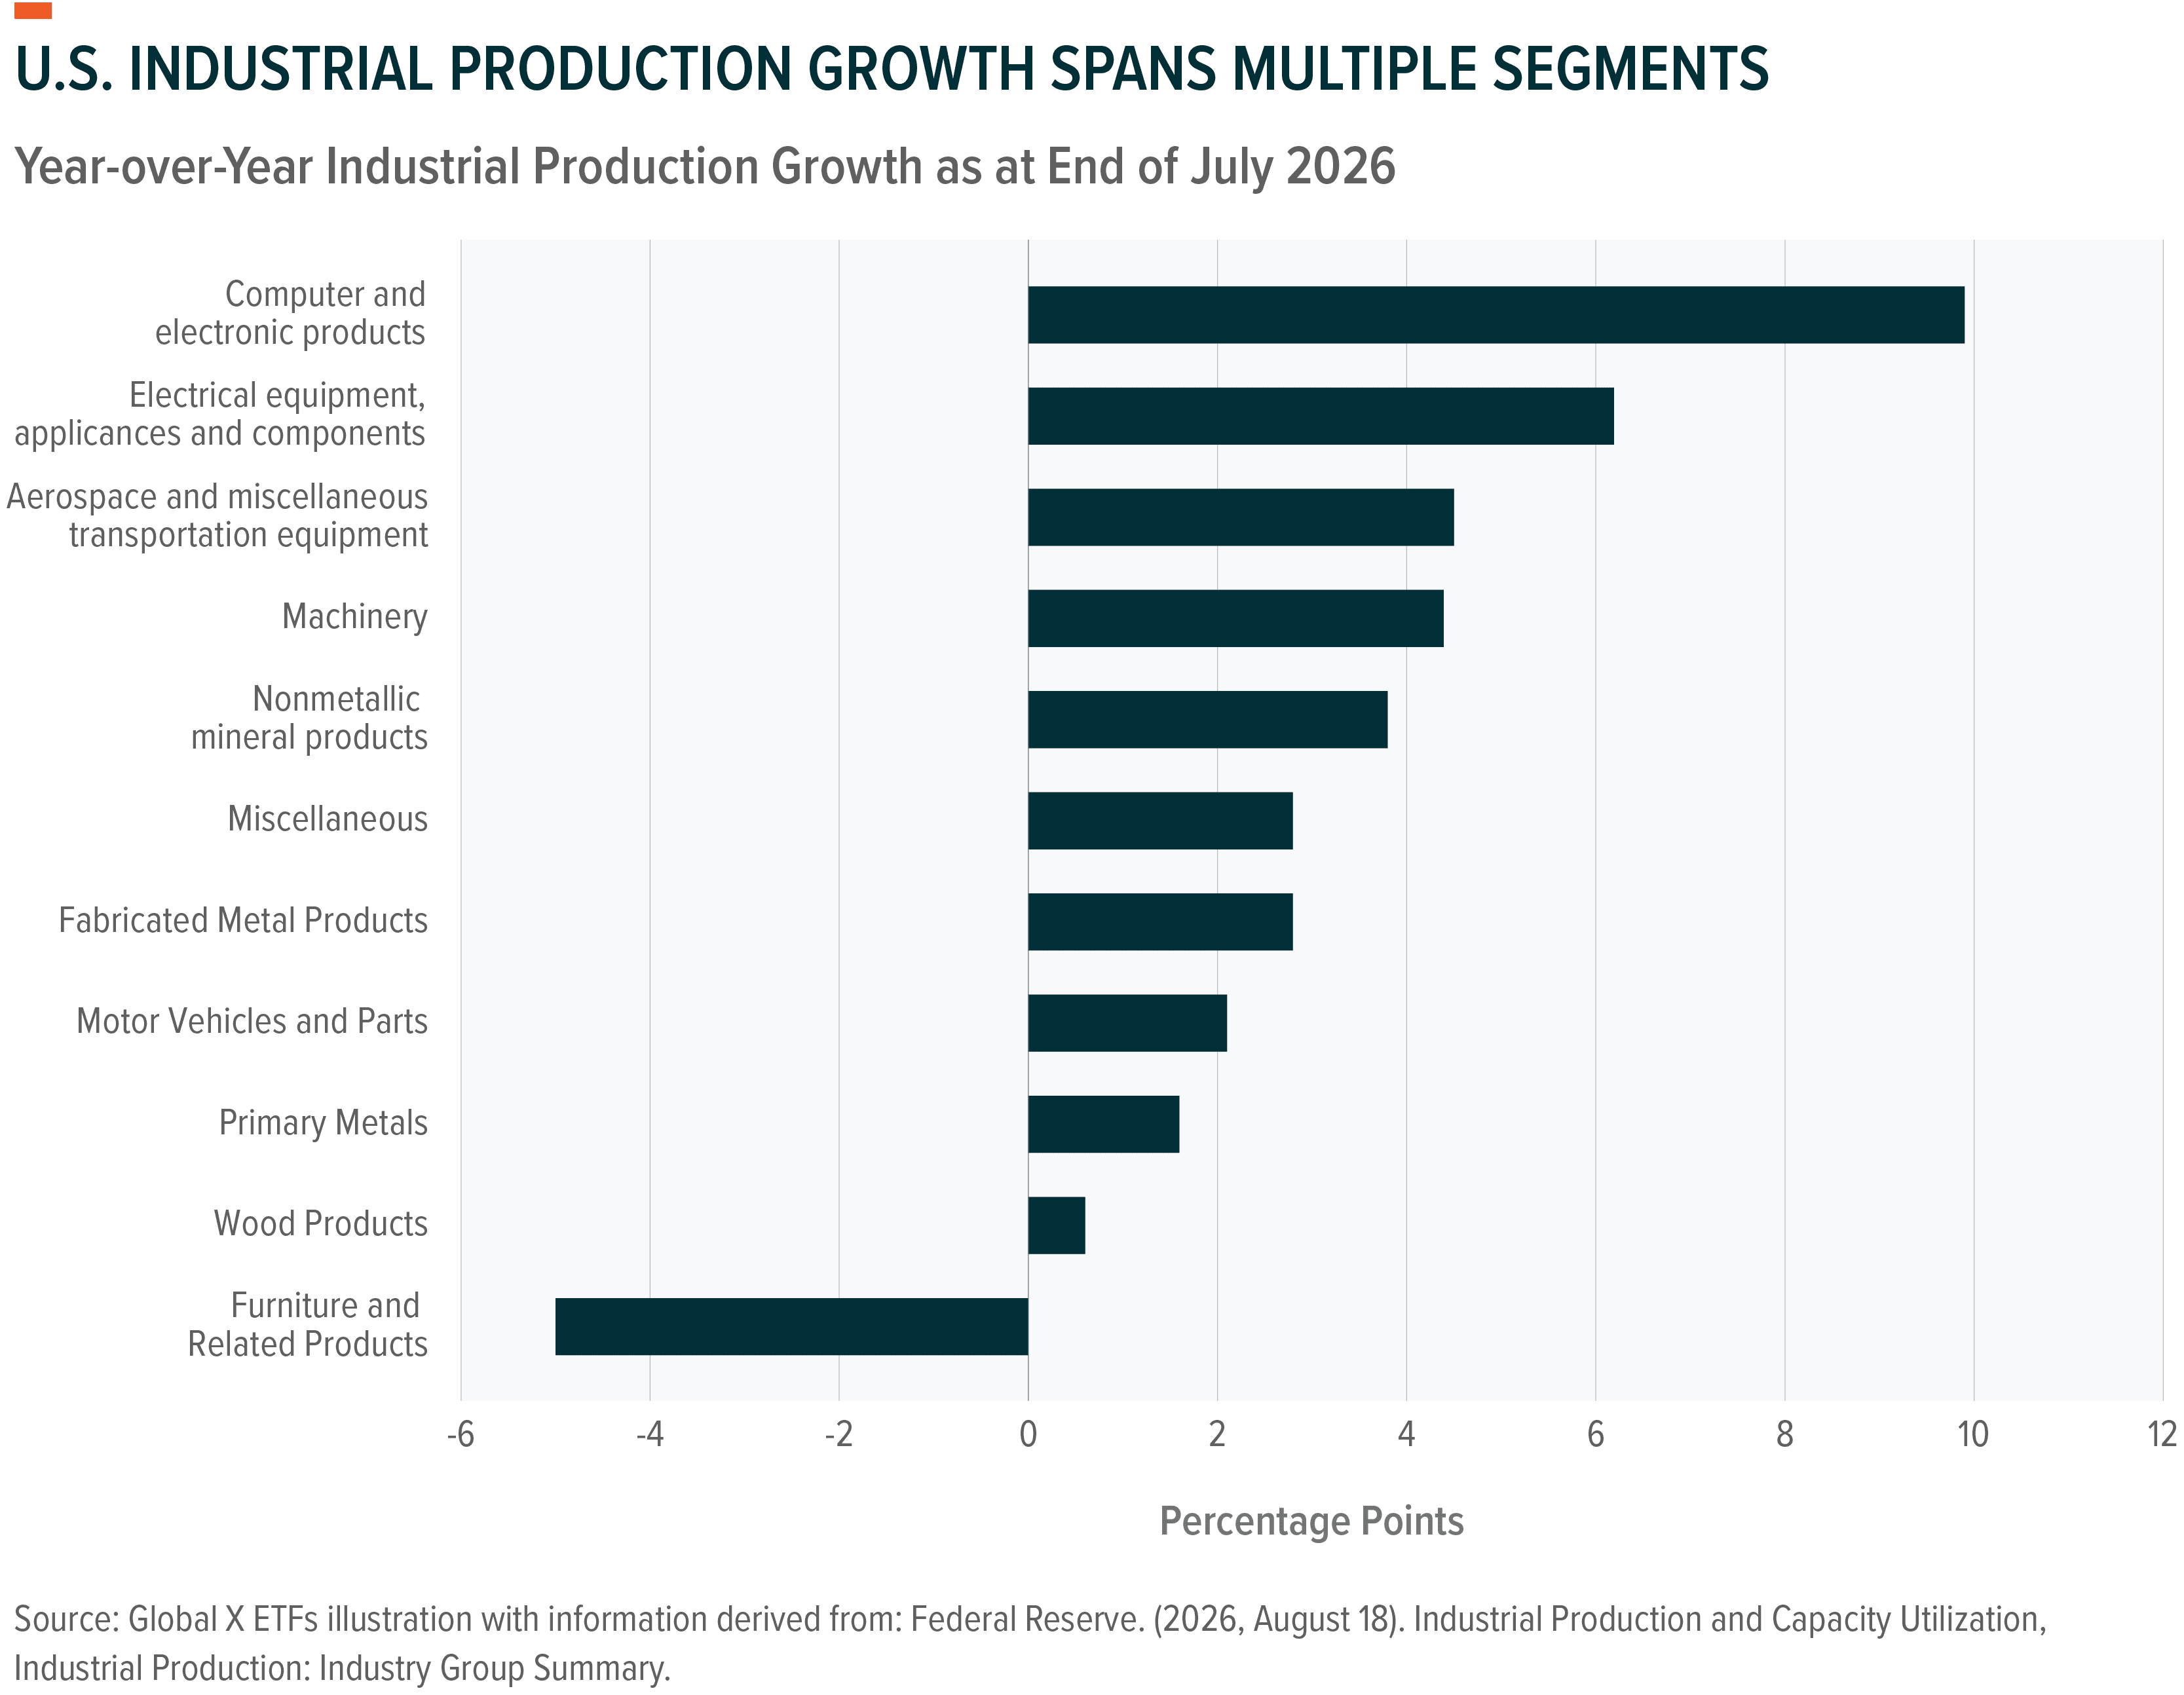
Hard economic data shows that the reshoring story, long viewed with scepticism, may finally be gaining operational traction. U.S. industrial production grew at a 3.9% annualised rate in Q2 2026 with 0.2% month-over-month growth in July.⁴ Durable manufacturing output, a cleaner production-side signal, rose 0.7% in July, maintaining broad strength across computer and electronic products, electrical equipment, aerospace and miscellaneous transport equipment, and machinery.⁵
The end-use signal is also improving, with business equipment, transit equipment, defence and space equipment, construction supplies, and materials pointing to firmer demand across markets tied to capital expenditure (CapEx) investment and industrial buildout.⁶
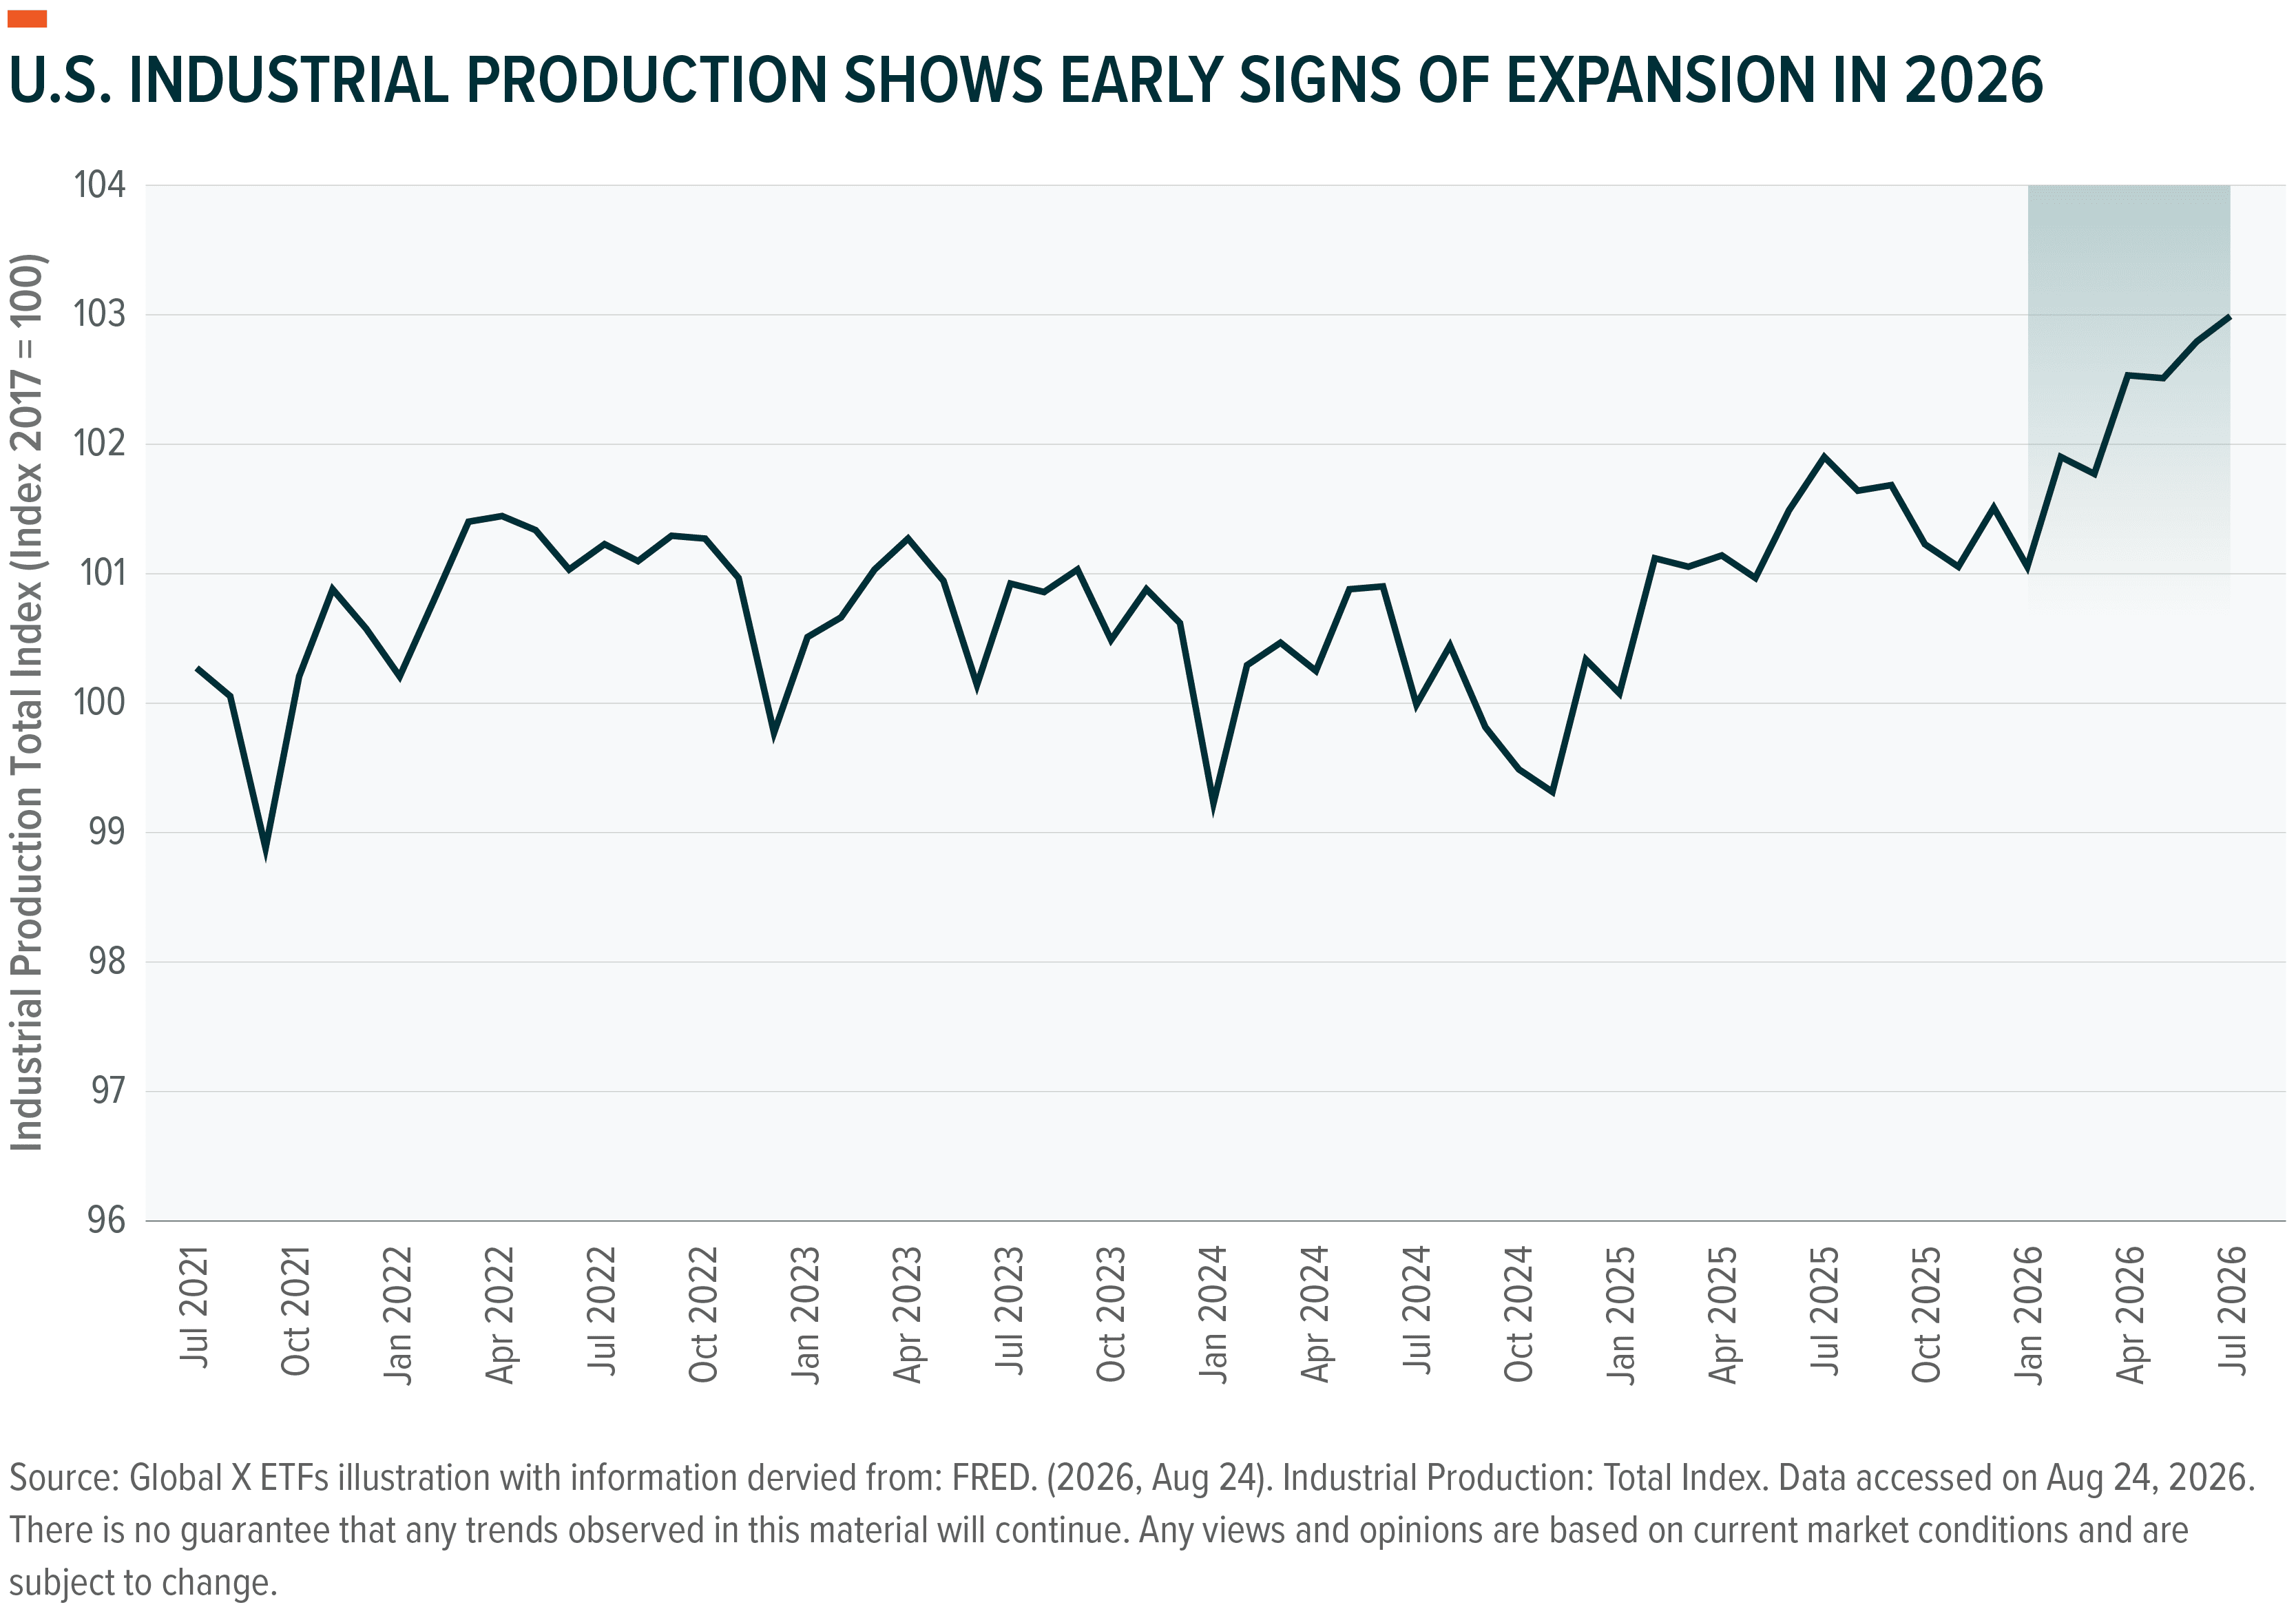
Survey data points in the same direction. ISM’s Manufacturing PMI rose to 55.6 in July from 53.3 in June, marking the sector’s seventh consecutive month of expansion after a 10-month contraction in 2025.⁷ Underlying drivers were also constructive, with New Orders strengthening, Production remaining in expansion, and Backlogs rising.⁸ S&P Global’s U.S. Manufacturing PMI confirmed the trend, remaining steady at 53.9 in July, with S&P noting that operating conditions “have now improved consistently for a year”.⁹
Policy-sensitive sectors add evidence of import substitution, a sign that domestic capacity is filling in to absorb demand. Steel imports fell 12.6% in 2025 following enacted tariff policy, while finished steel imports declined 17.1%.¹⁰ U.S. steel mill production has increased in 2026, suggesting that trade policy is beginning to affect domestic production in select markets.¹¹ Year-to-date in 2026, total and finished steel imports are down 19.6% and 22.1% respectively versus 2025, and down 21.6% and 25.3% compared to the prior 12-month period.¹²
While manufacturing employment had been in decline for a long period of time, July saw the first expansion for the first time in 33 months.¹³ The previous long-term contraction was seen as a critique of the manufacturing recovery but may have understated a structural shift toward a more automated, capital-intensive model, where output and capacity matter more than headcount. Manufacturing capacity utilisation was 76.0% in July, still 2.2 percentage points below its long-run average.¹⁴ These datapoints keep the most aggressive “reshoring boom” narrative in check, but do not undercut the groundwork taking shape for a real turn in domestic industrial activity.
The reshoring case firmly rests on capital that is already committed. Analysis indicates that companies announced roughly $1.42 trillion in planned U.S. manufacturing investment between January 2025 and mid-March 2026, concentrated in strategically important industries and led by semiconductors and pharmaceuticals.¹⁵ This complements nearly $769 billion in private investments committed towards reshoring strategic industries under the Biden administration.¹⁶
In a world shaped by geopolitical fragmentation, tariff risk, supply chain bottlenecks, and U.S.–China competition, critical industries need more domestic redundancy, and that need extends well beyond semiconductors and pharmaceuticals. Grid equipment, transformers, aerospace components, defence systems, industrial automation, and advanced electronics all sit at the intersection of U.S. economic competitiveness, supply chain resilience, and national security.
Recent corporate commentary reinforces that view, providing more evidence of capital flows into domestic industrial capacity tied to strategic industries such as the data centre buildout.¹⁷,¹⁸,¹⁹ In Q1 2026, Vertiv highlighted its efforts to expand domestic manufacturing capacity to meet rising demand for thermal management equipment.²⁰ Power equipment maker GE Vernova is scaling domestic production for on-site generation. The company has installed more than 280 new machines across its U.S. gas power factories over the past 15 months and added roughly 1,800 U.S. production workers in 2025 and 2026.²¹ Industrial automation provider Rockwell Automation reported demand from warehouse automation, semiconductors, and energy in fiscal Q2 2026. To meet this demand, the company is advancing its roughly $2 billion U.S. manufacturing expansion to reduce tariff exposure and shorten lead times.²² Eaton is tracking a U.S. mega-project pipeline of nearly $3 trillion across 866 announced projects and is expanding U.S. production capacity to capture its share.²³
Policy measures underpin the durability of the trend. The CHIPS Act of 2022 anchored semiconductor investment, and substantial incentives continue to roll out to support the production of strategic chips. Recent Defense Production Act authorities target domestic grid infrastructure and equipment, including transformers and related electrical equipment.²⁴ Meanwhile, rebuilding depleted munitions inventories due to the Iran conflict is likely to require further expansion of the defence industrial base.²⁵ The U.S. also recently committed $2 billion to seed domestic quantum computing production.²⁶
The reshoring opportunity is less about owning manufacturers broadly and more about owning the bottlenecks that make domestic production possible. The investable stack starts with infrastructure development, moves through automation and connectivity, and ultimately depends on power.
Before reshoring becomes a production story, it is a land, materials, engineering, and construction story. New capacity requires site preparation, roads, utilities, industrial buildings, equipment installation, and logistics, all of which drive construction spending through the infrastructure value chain. That backdrop creates potential opportunities across engineering and construction, raw materials, heavy equipment, and industrial transportation. Ageing U.S. infrastructure, increasingly under stress and in need of broad modernisation, adds another layer of tailwinds and extends the development pipeline.
— Global X U.S. Infrastructure Development UCITS ETF (PAVE)
The reshoring cycle has been concentrated in high-throughput, high-precision sectors like semiconductors, electronics, autos, and industrial equipment, where automation is the operating model rather than a productivity overlay. Higher U.S. labour costs, persistent skilled-labour shortages, and rising quality requirements all strengthen the case for robotics. The connectivity layer behind smart factories, including sensors and industrial software, stands to benefit alongside it.
— Global X Robotics & Artificial Intelligence UCITS ETF (BOTZ)
— Global X Internet of Things UCITS ETF (SNSR)
Reshoring arrives alongside AI data centre expansion, electric vehicle adoption, and broader electrification, creating a new demand cycle for electricity after years of flat growth. Factories need reliable, affordable, and scalable power, potentially positioning the companies that expand and harden the grid, add generation, deploy storage, and improve load management to emerge as the cycle’s winners.
— Global X U.S. Electrification UCITS ETF (ZAPP)
The U.S. manufacturing story could be steadily shifting from one of future promise to actual throughput. The factories, incentives, and capital expenditure plans are largely in place, while early signals from industrial production, ISM data, and policy-sensitive sectors suggest output could scale quickly to meet rising demand. With capacity increasingly in place, the key enablers of that throughput: infrastructure development, advanced automation, and next-generation power infrastructure, could become the next drivers of the U.S. manufacturing cycle.
This document is not intended to be, or does not constitute, investment research as defined by the Financial Conduct Authority.