
Europe

Gold has historically been regarded as a store of value, with its scarcity and global recognition supporting its role in long-term wealth preservation and portfolio diversification.¹ Gold miners may provide leveraged exposure to gold, with operational improvements creating potential for stronger cash flows. ² A context-sensitive responsible-mining framework may support the assessment of how effectively gold miners manage material risks, strengthen business resilience and contribute to sustainable development.³
The Global X Responsible Gold Miners UCITS ETF (GLDX LN) seeks to invest in companies that provide exposure to the gold mining industry by applying a responsible mining framework that incorporates sustainability screens, environmental impact metrics and selected social and governance indicators.
Below are highlighted some key characteristics of the gold market and the gold mining sector, as well as the sector's responsible approach.
Gold occupies a distinctive position in global financial markets as a real asset, reserve asset and potential safe haven.⁹ During periods of economic or geopolitical uncertainty, it has historically attracted demand for its potential diversification benefits and resilience when confidence in fiat currencies weakens.¹⁰
For centuries, gold has been regarded as a store of value, helping preserve wealth through market cycles thanks to its physical qualities of durability and scarcity. ¹¹ Gold is highly durable and corrosion-resistant; as a result, unlike many other commodities, gold produced over time remains in existence today held as jewellery, coins, bars, and central bank reserves, or used in other applications.¹² Yet gold is scarce, and the 'gold cube' helps illustrate this scarcity: if every ounce of the world's gold mined throughout history were placed side by side, the resulting cube of pure gold would only measure approximately 22.5 meters on each side.¹³
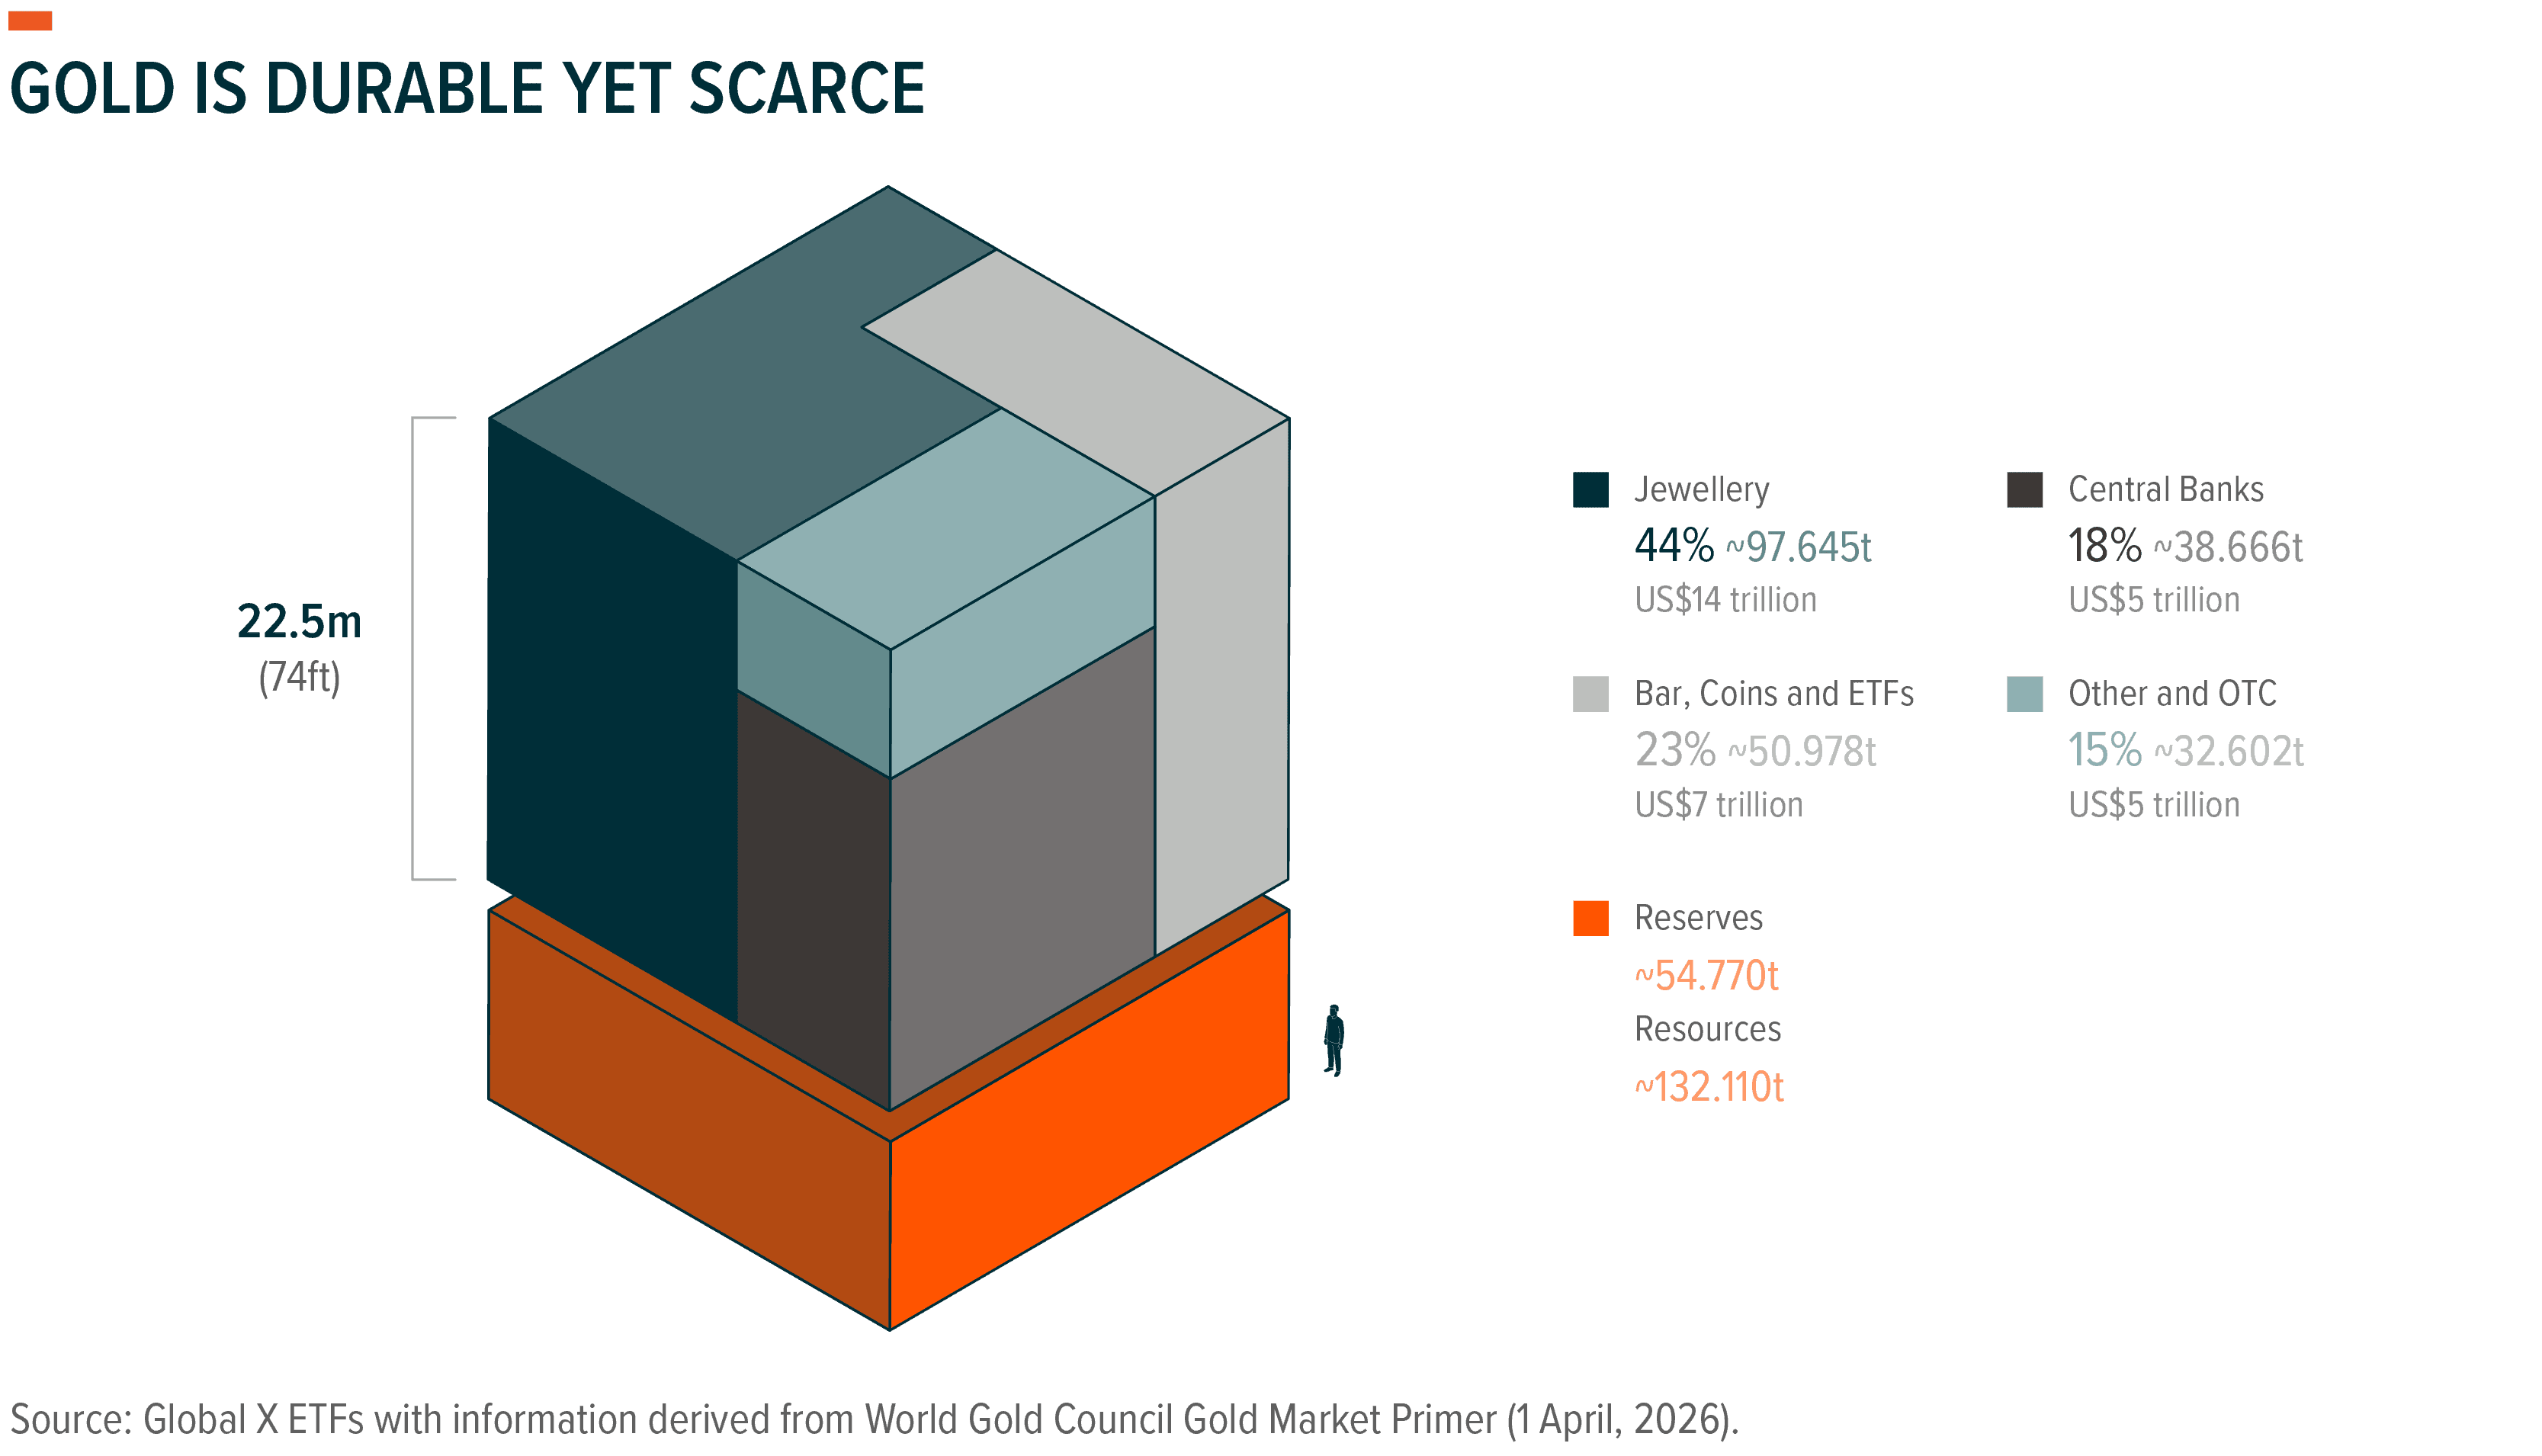
Gold demand spans jewellery, investment, technology and official-sector holdings, while supply is drawn from geographically dispersed mine production and recycled metal.¹⁴ This diversity may support market stability by reducing the market’s dependence on any one consumer group, region or source of supply.¹⁵
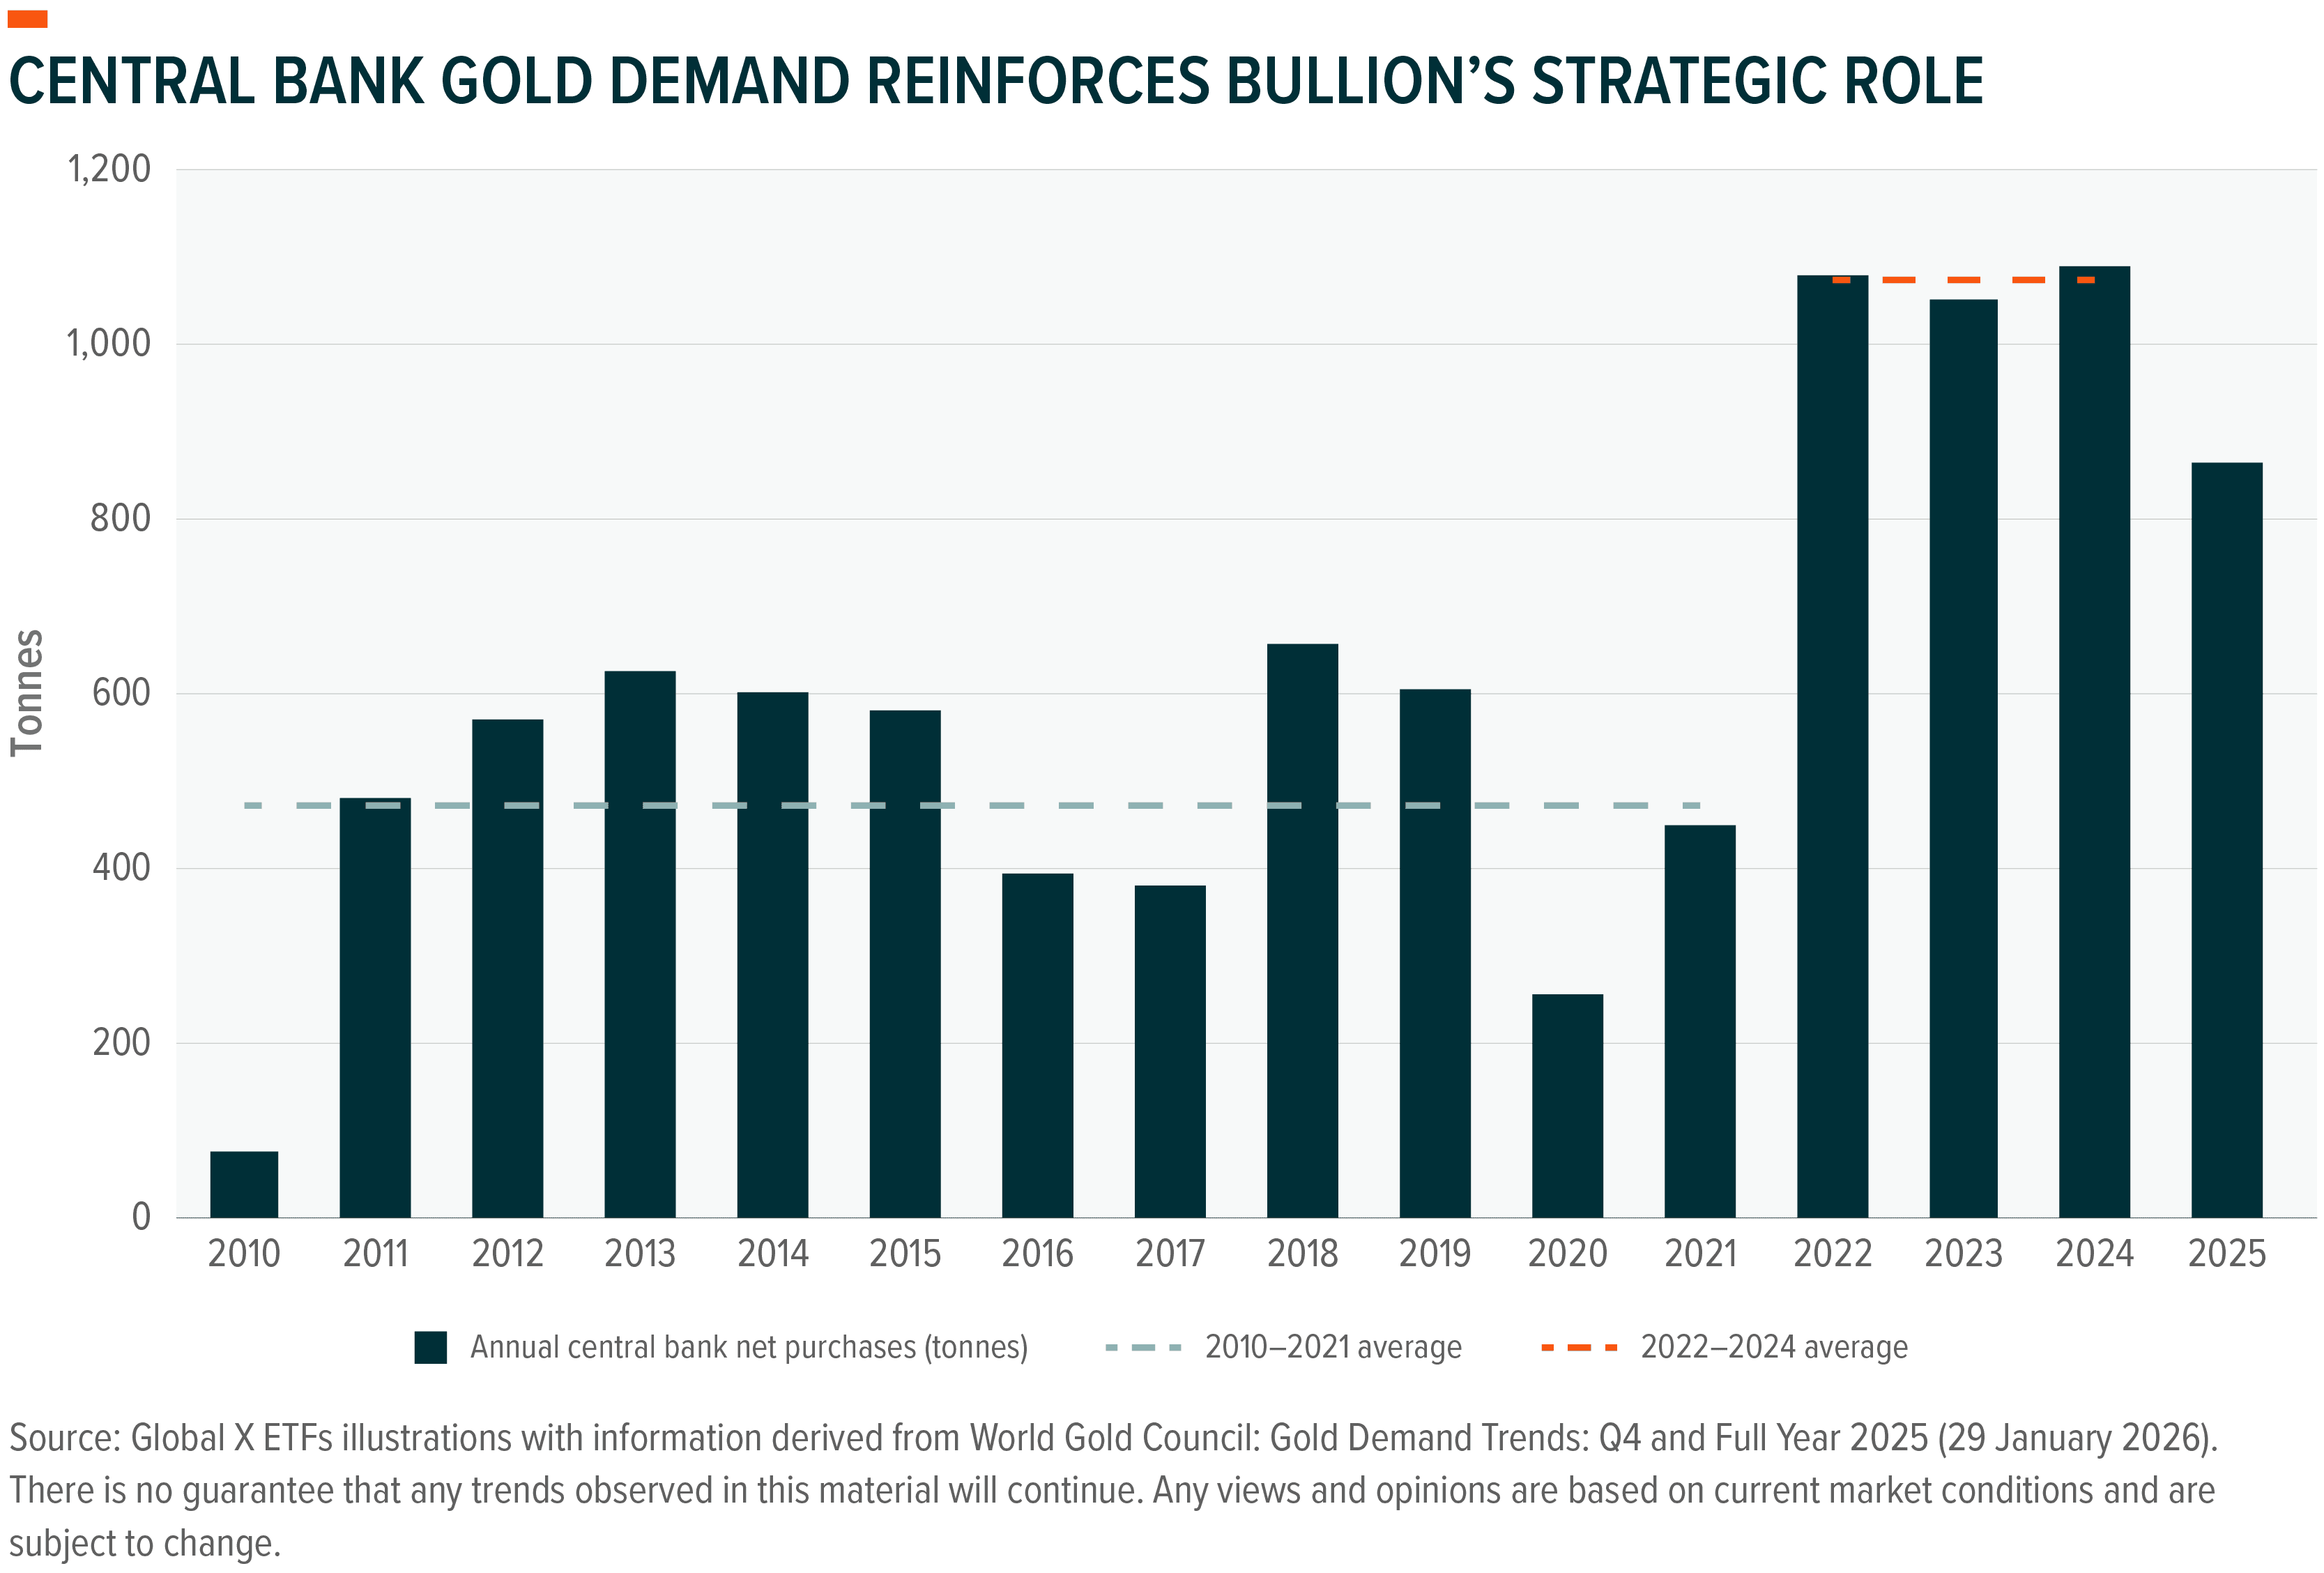
Central banks have become an increasingly important source of gold demand.¹⁶ Official-sector purchases remained elevated in 2025, after having exceeded 1,000 tonnes annually between 2022 and 2024 compared with an average of 500 tonnes per year over the preceding decade.¹⁷
A June central banks survey found that 89% of respondents expected global central-bank gold reserves to increase over the following 12 months, while a record 45% expected their own institution’s holdings to rise.¹⁸ Central banks cite crisis performance, long-term value preservation, diversification, and geopolitical risk mitigation among the reasons for holding or increasing gold reserves.¹⁹
The increase in official-sector gold holdings appears to form part of a broader reassessment of reserve composition amid geopolitical uncertainty and concerns about exposure to traditional reserve currencies.²⁰ Looking forward, sustained central bank demand may reinforce gold’s long-term structural outlook and therefore may create a favourable backdrop for gold mining companies, notwithstanding near-term interest-rate risks.²¹
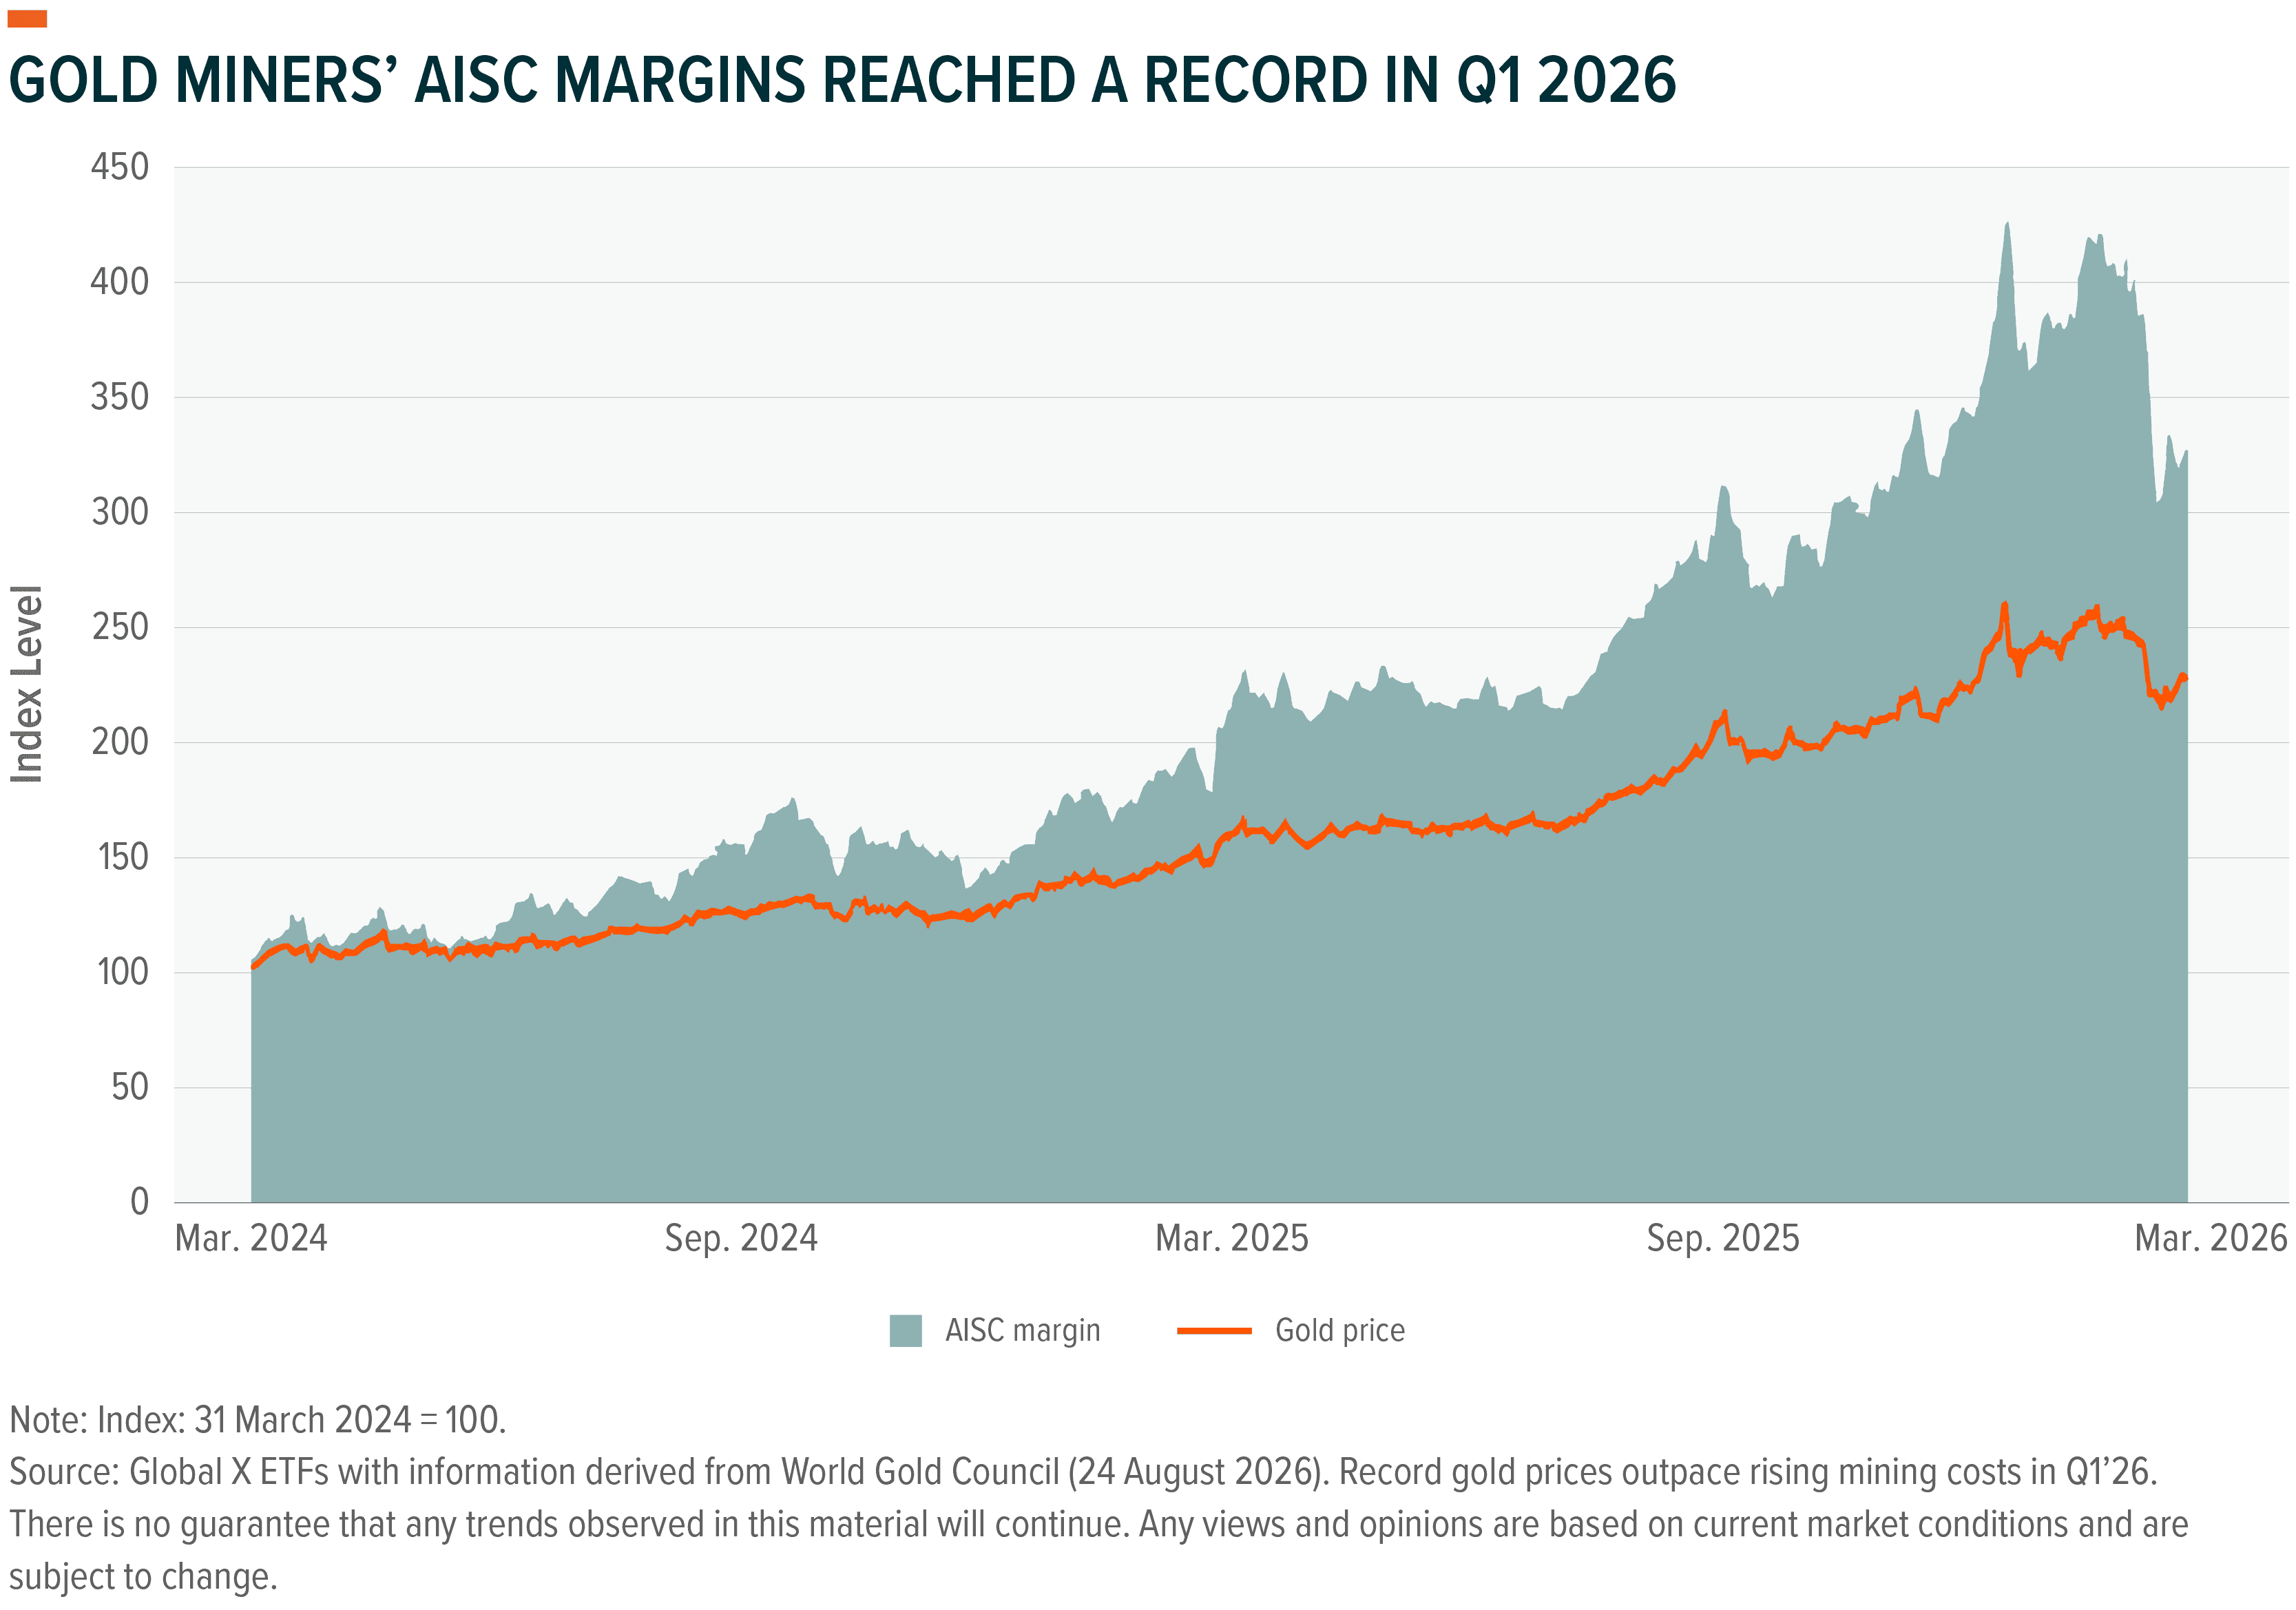
Gold miners can offer a differentiated way to gain exposure to gold. Unlike bullion, they are operating businesses that may generate earnings and cash flow. Because a significant proportion of mining costs may adjust more slowly than the gold price, sustained strength in gold may lead to greater increases in margins and profitability.²² This operational leverage means miners may outperform the underlying metal during favourable gold cycles, although it may also magnify losses when prices decline.²³
The long-term foundations of the opportunity may remain supportive.²⁴ For miners, gold’s structural sources of demand may be complemented by company-specific opportunities to create value through productivity improvements, exploration, reserve development and disciplined capital allocation.²⁵ Stronger cash flows may be used to reduce debt, fund growth, pay dividends or repurchase shares. ²⁶
Q1 2026 provides an example of this dynamic: global average all-in sustaining cost (AISC) margins—the difference between gold prices and AISC—reached a record US$3,076 per ounce, increasing 134% year-on-year despite continued cost inflation.²⁷ Average AISC rose 16% year-on-year to US$1,785 per ounce, while the average gold price increased 70%. ²⁸
During that period, producers maintained relatively disciplined spending and cost management compared with previous gold-price booms, with many holding net cash positions and returning cash to shareholders. ²⁹ The durability of these benefits depends on gold prices, production costs, investment requirements and operational execution. ³⁰
How investors assess the sector remains relevant as gold miners face operational disruption, cost inflation, commodity price volatility, and political or jurisdictional risk.³¹ A responsible approach to gold mining may help identify companies with stronger governance, environmental stewardship, safety standards and community relationships.³² These qualities can help maintain a licence to operate and protect the value of long-lived mining assets, making responsible practices a relevant consideration in risk management and business resilience. ³³
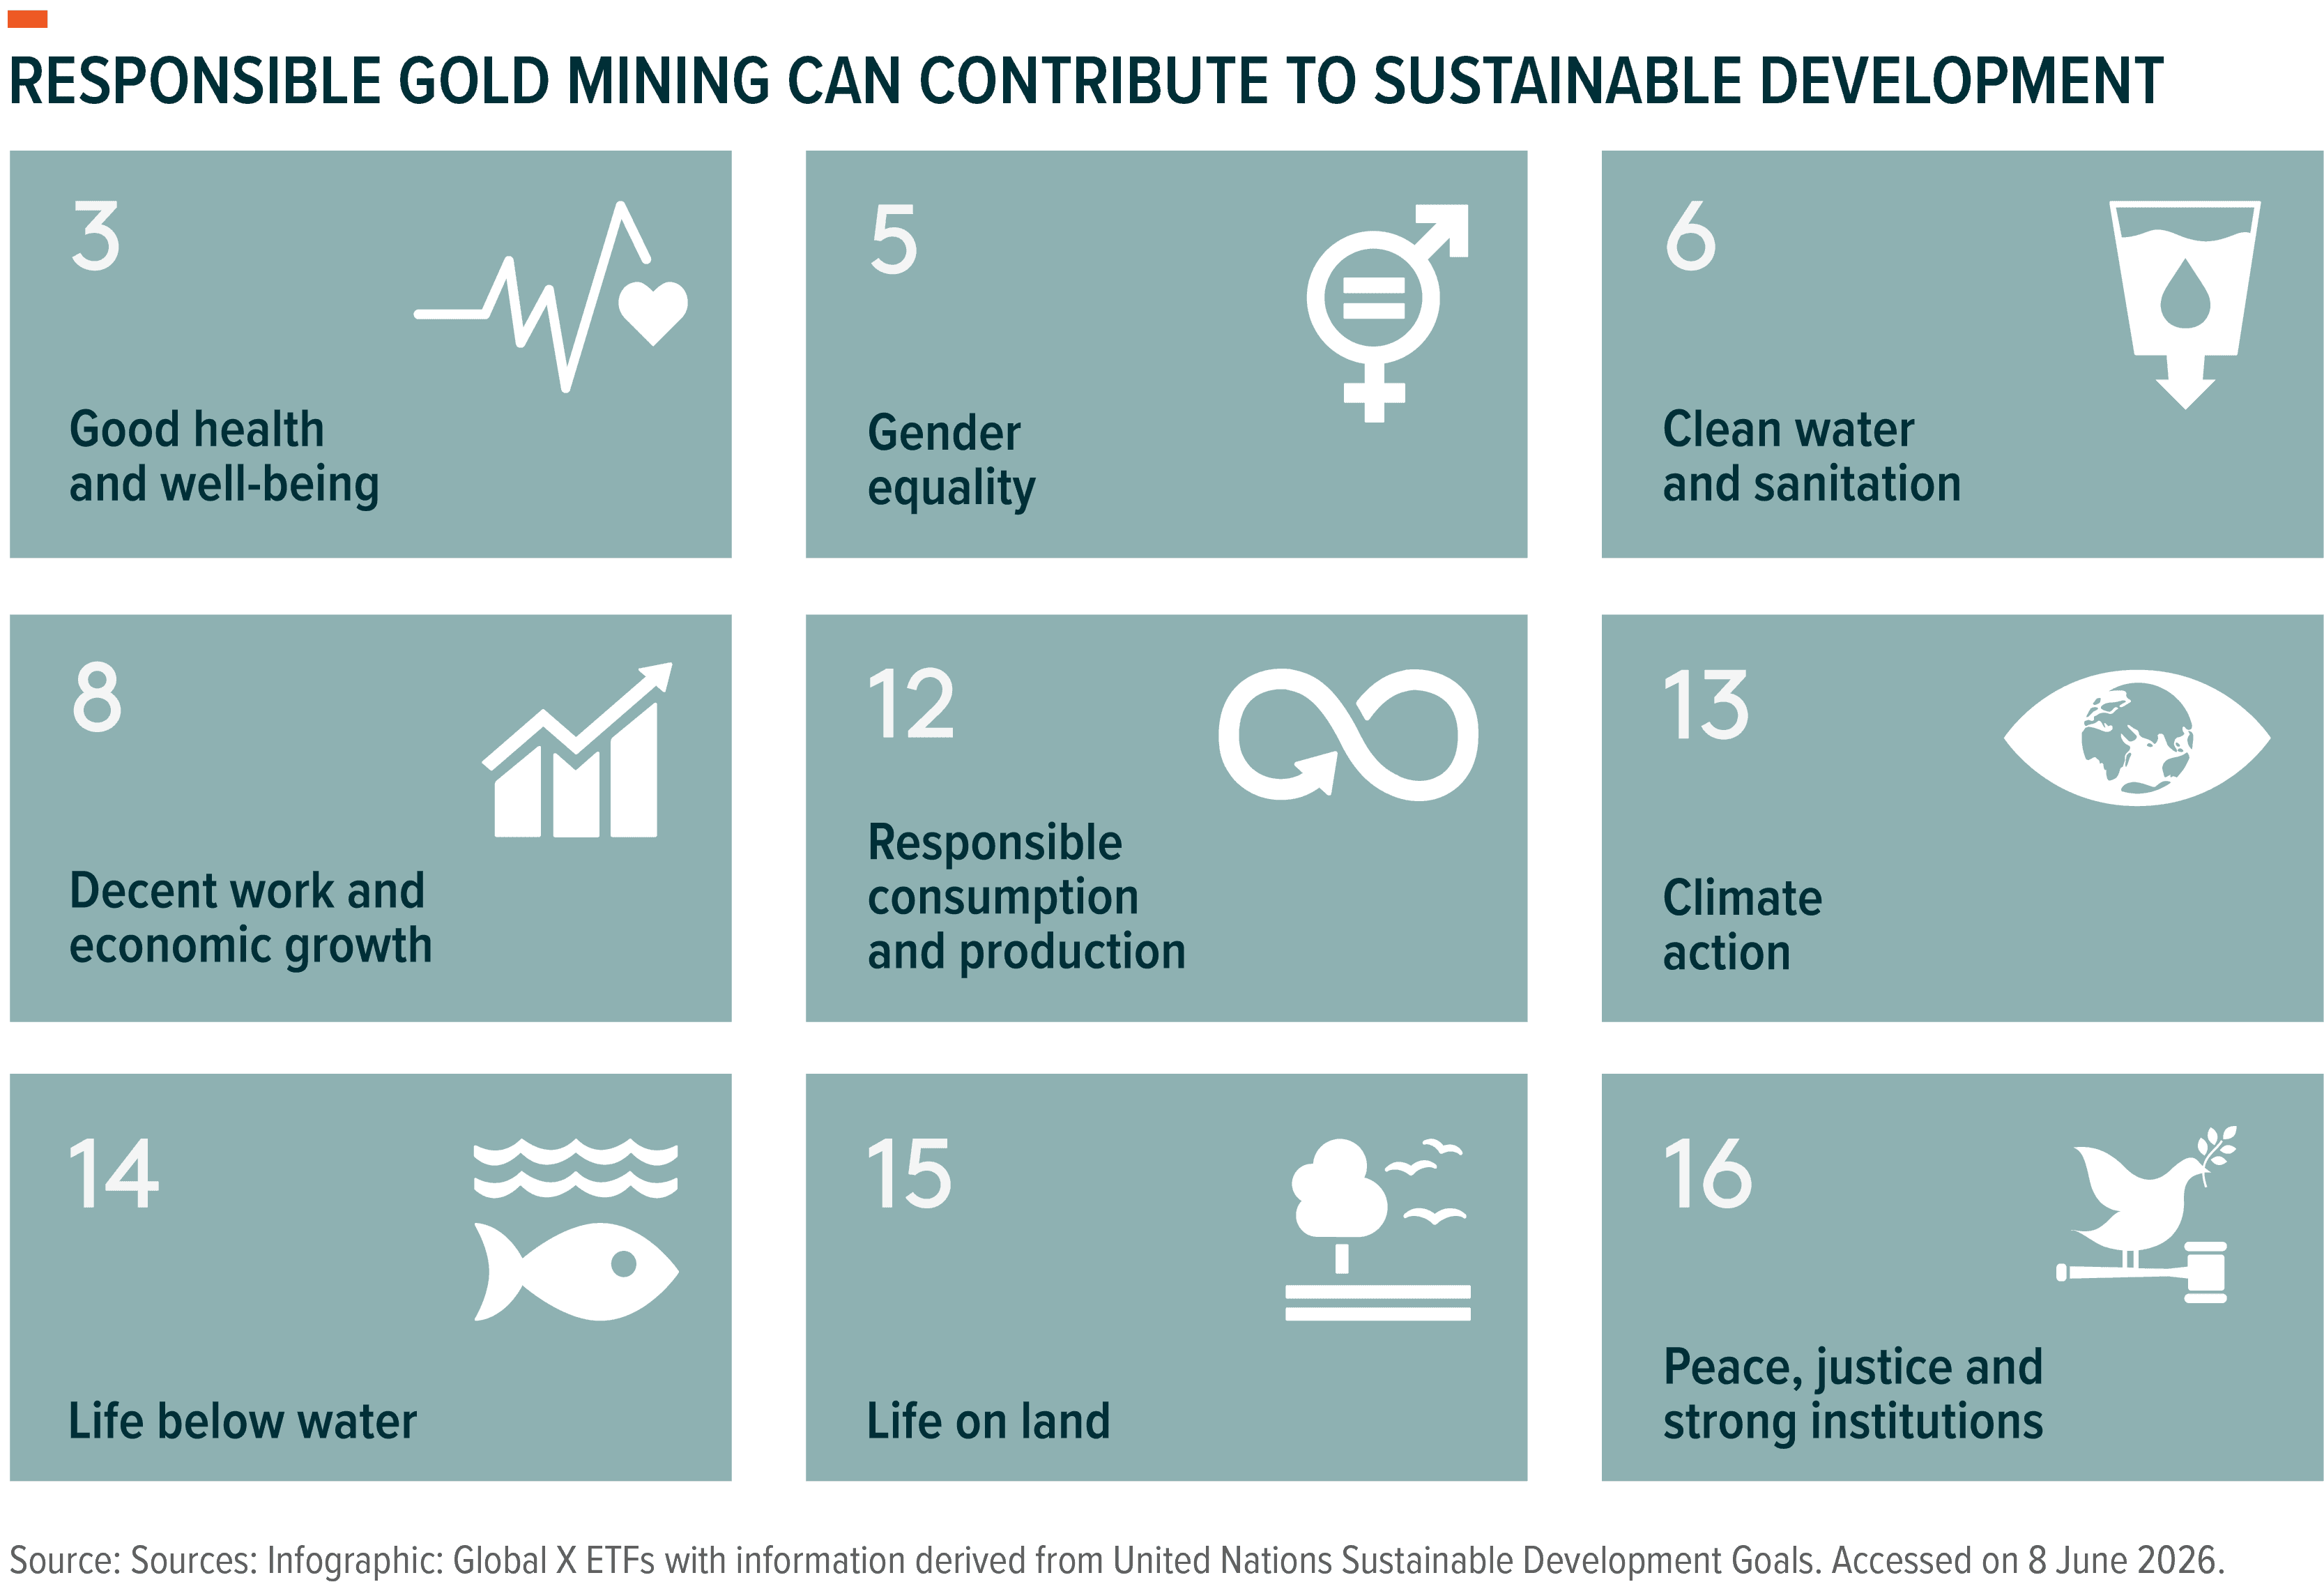
Responsible mining may contribute to the Sustainable Development Goals (SDGs) through employment, infrastructure development and community investment.³⁴ These potential benefits should be assessed alongside mining’s environmental and social impacts.³⁵ In gold mining, this requires attention to environmental stewardship, human rights, affected communities, sound governance, and the equitable distribution of benefits to host countries.³⁶ Applying an SDG lens could provide a systematic and transparent framework for assessing and weighting companies against defined sustainability indicators. ³⁷
Responsible mining may be assessed by how effectively policies and commitments are implemented and overseen in practice.³⁸ Independent assurance, where available and appropriately scoped, may provide an additional input into this assessment.³⁹ Appropriate practices are likely to vary according to the jurisdiction, operating context and stage of the mine lifecycle. ⁴⁰ Relevant factors may include water management, tailings safety, effects on communities, activities in conflict-affected or high-risk areas, and engagement with artisanal and small-scale miners.⁴¹
Responsible mining may therefore be viewed as an ongoing process of identifying, preventing or mitigating, monitoring and communicating impacts, rather than as a fixed designation. ⁴²
This document is not intended to be, or does not constitute, investment research as defined by the Financial Conduct Authority.
1. International Monetary Fund. (2026, March 3). Gold’s lasting luster. Finance & Development, 63(1)
2. Reuters (2026, January 26) Gold miner shares jump as bullion prices hit $5,100/oz record high
3. World Gold Council. (2019, September 12). Responsible Gold Mining Principles (RGMPs).
4. Ibid
5. Reuters. (2026, June 16). More central banks signal plans to increase gold holdings, WGC survey shows.
6. Bloomberg Dataset (2026, July 14) Gold price 30/06/2016 to 30/06/2026.
7. Bloomberg Dataset (2026, July 14) Gold price 30/06/2016 to 30/06/2026,Operating margins are the trailing 12-month for the NYSE Arca Gold Miners Index (GDM)
8. World Gold Council. (2019, September 12). Responsible Gold Mining Principles (RGMPs).
9. International Monetary Fund.(2026, July 9). Gold in Central Bank Reserves: Strategic Considerations, Market Risks, and Practical Guidance.
10. Ibid.
11. International Monetary Fund. (2026, March 3). Gold’s lasting luster. Finance & Development, 63(1)
12. U.S. Geological Survey. (2026, February 10). How much gold has been found in the world?
13. World Gold Council (2026, April 1) Gold Market Primer: Market size and structure.
14. U.S. Geological Survey. (2026). Mineral Commodity Summaries 2026: Gold.
15. Reuters. (2026, January 12). How investors buy gold and what fuels the market.
16. European Central Bank. (2026, June 11). The International Role of the Euro, June 2026.
17. Ibid.
18. Reuters. (2026, June 16). More central banks signal plans to increase gold holdings, WGC survey shows.
19. Ibid
20. European Central Bank. (2026, June 11). The International Role of the Euro, June 2026.
21. J.P. Morgan Global Research. (2026, June 9). Will gold prices hit all-time highs again in 2026?
22. PwC. (2026, June). Mine 2026: Ambition to Action.
23. Reuters (2026, January 26) Gold miner shares jump as bullion prices hit $5,100/oz record high
24. Reuters (2026, February 25) JP Morgan raises long-term gold price forecast to $4,500)
25. PwC. (2026, June). Mine 2026: Ambition to Action.
26. Ibid.
27. World Gold Council / Metals Focus. (2026, August 24). Record gold prices outpace rising mining costs in Q1’26.
28. Ibid.
29. Ibid.
30. World Gold Council / Metals Focus. (2026, August 24). Record gold prices outpace rising mining costs in Q1’26; PwC. (2026, June). Mine 2026: Ambition to Action; S&P Global Market Intelligence. (2026, August 12). H1 2026 Mining Analysis: Cost Inflation, Geopolitical Risk, and Commodity Divergence.
31. S&P Global Market Intelligence. (2026, August 12). H1 2026 Mining Analysis: Cost Inflation, Geopolitical Risk, and Commodity Divergence.
32. World Gold Council. (2019, September 12). Responsible Gold Mining Principles (RGMPs).
33. ERM. (2025, April 15). Sustainability that pays: Defining a credible business case for investing in sustainability in mining and metals.
34. World Gold Council. (2020, September 22). Gold Mining’s Contribution to the UN Sustainable Development Goals.
35. World Gold Council. (2019, September 12). Responsible Gold Mining Principles (RGMPs).
36. Ibid.
37. United Nations Development Programme. (2021, July). SDG Impact Standards for Enterprises: Version 1.0.
38. World Gold Council. (2019, September 12). Responsible Gold Mining Principles (RGMPs).
39. Ibid.
40. Ibid.
41. Ibid.
42. Ibid.